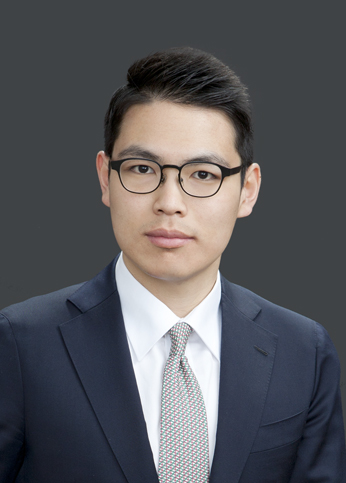
Lee, Se Bin
Introduction
Se Bin Lee is a Partner at Yulchon LLC, specializing in family business succession planning, inheritance and gift taxation, and a broad range of tax disputes and advisory serivces. Mr. Lee has a B.A. in Business Administration from Yonsei University and a J.D. from Seoul National University. From 2014 to 2023, he worked at Yulchon’s Tax Group where he has successfully represented and advised clients in complex tax matters and high-profile tax disputes. From 2023 to 2025, Mr. Lee served as a Research Judge at the Supreme Court of Korea where he conducted in-depth analyses of various tax cases and developed legal precedents that continue to influence tax litigation and policy in Korea. In 2025, Mr. Lee rejoined Yulchon LLC, and continues to leverage his expertise and unique insights to provide strategic tax advice to clients.
- 2024 University of Seoul, Graduate School of Science in Taxation, M.A.
- 2014 Seoul National University, School of Law, J.D.
- 2011 Yonsei University, Business Administration, B.A.
- 2025-present Partner, Yulchon LLC
- 2023-2025 Research Judge (Tax), Supreme Court of Korea
- 2014-2023 Associate, Yulchon LLC
- 2014 Admitted to Bar , Republic of Korea
- 2009 Certified Public Accountant , Republic of Korea
Korean, English
Awards/Recognition
- 2026 Rising Stars, Tax, Legal Times
- 2018 Grand Prize in Litigation, 1st Korea Legal Awards, Korea In-house Counsel Association and Money Today
Speech/Presentation
- 2023 2022 Local Tax Case Conference, Winter Conference, Korea Local Tax Association
- 2021 2020 Tax Case Conference (Property Taxation), Winter Conference, Korea Tax Forum
News/Publications
Reasons for Allowing Retroactive Re-Evaluation of Land by the Tax Authorities for Market Price Evaluation and Its Limitations, Commentaries on Supreme Court Decisions, Vol. 140(2024)
Timing of Mixed Approval, a Requirement for Partial Product Taxation Under Article 188 of the Customs Act, Commentaries on Supreme Court Decisions, Vol. 138(2024)
Scope of Market Price That Corresponds to Acquisition Price Deductible as Necessary Expense When Calculating the Capital Gains Tax on Foreign Assets, Commentaries on Supreme Court Decisions, Vol. 138(2024)